There are two main facilities on a family home loan that should exist in anyone’s tax planning toolbox but unfortunately, they are often misunderstood or improperly used.
There are two main facilities on a family home loan that should exist in anyone’s tax planning toolbox. Unfortunately, they are often misunderstood or improperly used.
Variable home loans are generally more likely to offer features like an offset account or a redraw facility, which are two alternative options that help homeowners reduce their mortgage repayments.
Both tools have contributed to the record rate of debt repayments seen across the country.
Bankwest, for example, said that in March 2022, more than 90 per cent of customers were ahead on their home loan repayments. The average months by which customers were ahead (around three years), increased by 45 per cent.
Their data showed a huge uplift in the volume of savings put into home loan offset accounts. From June 2019 to March 2022, offset account balances grew by 63 per cent – nearly triple the rate of personal savings growth for the period of 23 per cent.
The surge in home loan repayments was matched by a rapid uptake in new home loan offset accounts linked to an eligible home loan, enabling households to use existing savings to reduce their current home loan balance.
Comparison researchers Canstar found that all variable rate home loans and a majority (61.7 per cent) of fixed rate home loans offer a redraw facility.
Canstar analysis of the owner-occupier and investment home loans found that the vast majority of variable rate loans (93.7 per cent) – along with over one-third of fixed rate loans (35 per cent) – offer a full offset account.
So, what exactly are these two, often misunderstood but common, home loan features?
Offset account
This is a standard bank account that is linked to your loan account. The offset account will normally be with the same financial institution as the mortgage provider.
The offset account effectively reduces the loan balance by the amount of money in the offset account, thus reducing the interest component on the monthly loan repayment. This only works with variable rate loans, not fixed rate loans.
This is an ideal location for your emergency cash-float and where your salary or income should be deposited.
The money in an offset account is technically your money, not the bank’s or an early loan repayment. This means that if you take money from the offset account to buy an income producing asset like shares, the interest charged on that purchase cannot be claimed in your tax return.
Purchasing investment assets in this way keeps the loan with its original use, being the family home, not the new asset purchase and the interest not a tax deduction.
So, the main benefit of an offset account compared to an ordinary transaction account is that the money you put into it is ‘offset’ daily against the balance of your home loan, and interest is charged against this reduced amount, rather than the full outstanding balance of your home loan.
Redraw facility
The redraw facility provides the ability to pay down your home loan mortgage in advance and at any time while the loan is active, and then withdraw some or all the amounts paid in advanced.
The act of redrawing alters the usage of the withdrawn amount into a new loan, secured against the family home but assigned to its next use.
If the next use of that money is to generate taxable income, then the interest cost on that new loan (redrawn) amount is tax deductible and ‘good debt’.
If the redrawn amount was used to buy a boat or go on a family holiday, which do not produce taxable income, then the interest cost on this new loan is not tax deductible, and the new loan is considered ‘bad debt’.
The family home, or as we like to refer to it, ‘The Lazy Uncle’, can utilise the redraw facility to maximum advantage.
This works during periods of low interest rates where the cost of borrowing is less than what can be earned by investing in tax advantaged assets, like Australian shares, investment properties or interest-bearing investments, such as fixed interest bonds.
By using the redraw facility and structuring the new loans into sections of variable and multi-year fixed rates for peace of mind and repayment stability, a tax planning strategy starts to emerge where additional cashflow produced can help with:
accelerated reduction of the family home loan
additional income to support living expenses
additional superannuation contributions.
When it comes to funding early, semi or full retirement, using the redraw facility and putting the ‘The Lazy Uncle’ to work is an effective tax planning strategy to consider well in advance of leaving full employment or paying off the family home loan too soon.
Offset account or one-off lump sum repayment into a redraw facility: impact with a $500,000 loan at 3% over 30 years
Offset/redraw amount at start of loan
Total interest paid over life of loan
Interest saved
$0
$258,887
–
$5,000
$251,677
$7,210
$10,000
$244,640
$14,247
$20,000
$231,070
$27,817
Source: Canstar. Based on a $500,000 loan with an interest rate of 3%, repaid over 30 years with principal & interest repayments. It is assumed that the offset account balance is kept constant at the specified amount for the entire loan term, or alternatively that the lump sum repayment of the specified amount is made at the start of the loan. Calculations do not take into account any fees that may apply.
Regardless of which strategy is adopted, any extra money paid off on a mortgage or kept in an offset account could save a significant amount in interest in the long run.
But features such as an offset account or redraw facility, as well as refinancing in pursuit of a better deal, can also add costs to a home loan in the form of additional fees or a higher interest rate and may have tax implications, so it’s always worth seeking professional advice to identify the best approach.
With research and patience, subdividing land can provide property investors with significant returns while also addressing housing affordability and supply issues.
Subdividing land for infill developments in suburbia is lauded as one solution to alleviating affordable housing undersupply and also presents an opportunity for investors.
Though not without barriers, typically due to government regulations, infill sites do offer positives, such as having water, electricity and internet, already connected.
Property investor benefits
“Many people have trepidation about building and investing in today’s market, with interest rates and inflation figures rising, but we know inflation is going to be high, so as long as interest rates are lower than the inflation rate, you’re still going to be in front,” Summit Development’s Senior Development Consultant, Ewan McConnell, said.
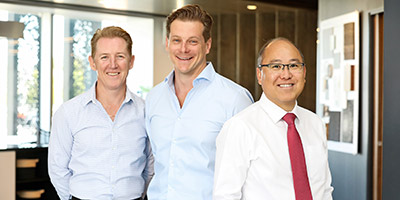
Summit Development Consultants Ewan McConnell, Adrian Johnson and Quentin Lau.
“The bigger picture is that Perth is still undervalued and other markets are starting to muscle in, which is why we strongly encourage our clients to consider a subdividable build-to-rent strategy, as you have the benefits of tax deductions, depreciation, compounding capital growth and rental income that could be paying off your repayments,” Mr McConnell said.
“Given these factors, it’s easy to see why Perth’s property market has been drawing the attention of astute property investors.
“Property is not a speculated, short-term investment, it’s a long-term, stable growth strategy and investors have the potential to maximise their potential and make the most of historically low vacancy rates.”
Perth’s premier rezoned target suburbs
Quentin Lau, Senior Development Consultant, Summit Developments, said investors in Perth infill areas should consider proximity to Perth’s CBD and infrastructure or proposed activity centres such as universities, hospitals, shopping centres and public transport.
“Generally, blue-chip suburbs are going to give you the best return on investment,” Mr Lau said.
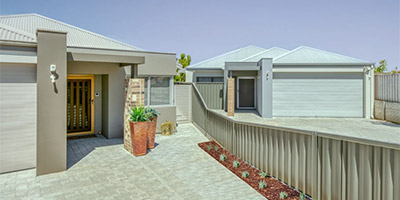
A Perth duplex called Kardinya is 747m2 with two single storey, 4×2 homes with theatre rooms. After purchasing the development site the client sought to achieve two street front homes to the 18.5m wide duplex site.
“Areas such as Cannington, Beckenham, Gosnells, Kelmscott, Maddington and Armadale tend to have higher development costs in relation to site soil conditions and drainage requirements and, therefore, are not always favourable for developers.”
Melbourne’s top tip subdivision suburbs
Well before the fluid property climate of the 2020s, the Office of the Victorian Government Architect (OVGA) and Monash Architecture Studio (MAS) released in 2011, the Infill Opportunities report, based on research by MAS, Swinburne University and RMIT University for the Australian Housing and Urban Research Institute (AHURI).
Key findings included strategic locations for infill redevelopments in Melbourne’s middle suburbs being identified as within a seven to 25 kilometre radius of the CBD, being suburbs developed between 1950-1970s, having close proximity to public transport and being outside areas with heritage overlays.
“Selection of lots by their width and depth, as opposed to lot area, is a more effective method of determining suitable development sites.
Common lot sizes in the middle suburbs range from 15-16m in width and 38-43m in depth,” the report suggests.
Long-term subdivision benefits
“Adding value via subdivision is, over the long term, a powerful and relatively safe option worth considering,” Steve Janes, an aussieproperty.com licensed real estate agent, said.
“I’m a huge advocate for engineering one residential home into two or three properties,” he said.
“Of course, subdivision isn’t without its challenges and the process can be complex, expensive, and time consuming, however, the accelerated uplift in capital value will over the medium term increasingly eliminate risk.
“This is despite what you initially pay for the property, within reason of course.
Steve Janes, Licensed Real Estate Agent, aussieproperty.com
“Also known as land banking, the strategy leans on maximising future profit by securing today’s land price.
From the purchase date (day the purchase contract is signed) the end development value shall appreciate at a greater dollar value than a single dwelling (without development prospect) of the same value,” Mr Janes said.
“Indeed, conditional on project delivery, the compounding effect is significant and is the main vehicle for above average performance.”
Over time, uplift in land value can contribute toward construction funding and development completion, activating the tax efficiency of a brand-new investment property.
“In the long term, you can benefit from a diversified portfolio with two or more properties while having only paid one stamp duty.
“Subdivision can be a good property strategy for those looking to create value in a property, maximize its potential use, or invest in real estate,” he said.
Subdivision and housing affordability
Urban Development Institute of Australia National (UDIA) President Max Shifman says it is the right time for bold initiatives that bring all property providers together and bolster land supply to resolve the affordable and social housing shortages.
He acknowledges the Federal Government’s new National Housing Supply and Affordability Council Bill (HAFF) as a ‘golden opportunity’ for government, community housing and private providers to pull together to resolve these shortages.
“We now face the stark reality that Australia needs 45,000 new affordable and social housing each year just to keep pace, yet we are only managing around 8,500 dwellings through government and Community Housing Providers,” Mr Shifman said.
“The decades long decline in new housing supply is a result of a lack of development-ready land due to a lack of enabling infrastructure, increasing cost imposts and inefficient planning processes.
“In addition, up to 60 per cent of zoned housing land is prevented from being built on because of straightforward issues.
“The result is that it can take six years or more to finish building a new house because of planning and approvals,” he said.
Barriers to successfully subdividing
The Victorian Infill Opportunities research demonstrates a range of design strategies for improving the density, quality and performance of small-scale infill housing and identifies the existing planning controls and industry trends incongruous with achieving better redevelopment outcomes.
Current barriers include regulated building setbacks that limit the potential and restrict optimum use of typical suburban sites, plus a growing demand for ensuites to all bedrooms and an expectation of double garages integrated with a dwelling structure are challenge for well designed, smaller infill housing proposals.
A new barrier for Victorians is the recent state government announcement that it would not allow landowners and developers to claim deductions for the costs of rezoning land under its incoming Windfall Gains Tax.
Developers and landowners in Victoria will be subject to the new tax at the rate of 50 per cent of any value gain of more than $100,000 that occurs when land is rezoned, from 1 July.
Craig Whatman, Executive Director Tax Advisory Group, Pitcher Partners.
Craig Whatman, Executive Director Tax Advisory Group, Pitcher Partners, said not allowing developers to claim deductions for pre-rezoning costs would increase the price of house and land packages and act as a deterrent to development activity.
“It had been hoped that the Treasurer would use the power prescribed by the Windfall Gains Tax legislation to allow for deductions to cover a range of costs ordinarily incurred by landowners and developers in the lead up to a rezoning decision,” Mr Whatman said.
“Many of these costs are incurred as a result of requirements imposed by local and state governments as well as other regulatory bodies and cannot be avoided.
“In our experience, increases in land value are not solely attributable to a rezoning decision nor are decisions to rezone likely to be made without the landowner and/or developer’s significant investment in the process,” he said.
“The government’s decision to ignore the costs incurred in the pre-zoning phase will result in an effective tax rate that is higher than the 50 per cent prescribed in the legislation and could ultimately discourage private investment in the rezoning process.”
Subdividing can be profitable with research
Perth house prices continue to rise and Summit’s Senior Development Consultant, Adrian Johnson, says there’s no better time than now to look into subdivision strategy in that city.
“After three years of record growth, Perth remains the most affordable capital city in Australia to buy property in and on top of that, the state continues to face a housing and rental crisis, with Perth’s vacancy rate dipping to a historically low 0.4 percent.”
aussieproperty.com’s Mr Janes concludes it’s important to carefully consider the potential benefits and challenges before embarking on a subdivision project.
“Work with experienced professionals who can guide you through the process.
“With the right approach, subdivision can be a powerful tool for outperforming market growth and without the need of hoping for a significant market correction that may or may not arrive.”
Article Q&A
Is subdividing a profitable form of property investment?
Property experts say subdivision isn’t without its challenges and the process can be complex, expensive, and time consuming, however, the accelerated uplift in capital value will over the medium term increasingly eliminate risk. Adding value via subdivision is, over the long term, a powerful and relatively safe option worth considering.
Where are the best and worst places to subdivide in Perth?
Areas that have undergone rezoning or where there are proposed upgrading plans, such as shopping centre redevelopment sites, include Booragoon, Kardinya, Kensington, Wilson, Padbury, Craigie and Karrinyup. Areas such as Cannington, Beckenham, Gosnells, Kelmscott, Maddington and Armadale tend to have higher development costs in relation to site soil conditions and drainage requirements and, therefore, are not always favourable for developers.
Which are Melbourne’s best suburbs to subdivide property?
A Victorian Government report’s key findings on strategic locations for infill redevelopments identified Melbourne’s middle suburbs within a seven to 25 kilometre radius of the CBD, developed between 1950-1970s, and with close proximity to public transport and being outside areas with heritage overlays as being ideally located for subdivision. The study focused on Essendon, Preston, Burwood East, West Footscray and Doncaster.
Underquoting remains a major issue in the real estate industry, prompting the Victorian Government to launch a dedicated taskforce, while other states have issued relatively few, if any, infringements for the widespread practice.
The scourge of illegal underquoting continues to waste the time and money of property buyers and the varying levels of action – or inaction – by the states suggests the problem will not be eradicated soon.
An agent is underquoting the selling price of a residential property if they make a statement or publish an advertisement about its price that is less than their reasonable estimate of the property’s likely selling price.
Underquoting laws are designed to ensure that buyers don’t waste money and time on property inspections, getting reports and attending auctions for properties that will likely be out of their price range.
Media reports have suggested that up to 80 per cent of properties were estimated to be underquoted in Victoria and industry professionals have told API Magazine that the situation is no better in New South Wales or Queensland.
Despite these claims, the number of infringements being issued against perpetrators is relatively low in all states, while there were none issued in Queensland this year.
Allen Habbouchi, Head of Project Sales and Distribution, aussieproperty.com, said underquoting gives buyers false hope.
“Underquoting may actually deter buyers from entering the market at all, as they start to lose confidence and hope with the whole experience,” he said.
Mr Habbouchi said properties in Sydney were routinely underquoted and estimated it would rival the 80 per cent of properties advertised, as claimed with Victoria.
Deterrent value
Consumer Affairs Victoria (CAV) recorded 1,466 underquoting inquiries and complaints in the state from 1 July 2021 to 31 July 2022, with just 48 infringements and 171 official warnings eventuating. This compared to 977 contacts in 2019-20, and 1,218 in 2018-19.
NSW Fair Trading issued 161 penalty infringement notices for underquoting and related offences. Each case was fined $2,200. Agents in Sydney usually charge a commission of about 2 per cent on sales, meaning the revenue on a median house price in the city of $1.6m would be about $32,000.
Mr Habbouchi said the fines and current laws were not serving as a deterrent.
“Agents purposely underquote in order to get the numbers for auction but RP Data and CoreLogic also have a lot to answer for, as their valuation price guide varies between 20-30 per cent in some instances, which does not help consumers at all.”
Queensland’s Office of Fair Trading (OFT) said it monitors the marketplace and conducts targeted proactive compliance checks throughout the year.
“No trends or concerns in relation to underquoting have been identified and there have been no infringement notices issued for underquoting in Queensland this year.
“The OFT has received nine complaints this year from consumers raising matters associated with property pricing, including concerns about properties being marketed without a price, and where the initially listed sale price was later increased, however, the OFT is not aware of any consumers being financially impacted in relation to these.”
Melinda Jennison, Buyers Agent, Streamline Property Buyers, said in Brisbane, unlike Sydney and Melbourne, quote ranges are not provided to buyers prior to auction so there is rarely a price guide provided leading up to an auction.
“For private treaty sales, a lot of properties in Brisbane are still being listed without a price,” she said.
“Where buyers can be misled is when a property has been filtered at the back end of real estate portals with a price range that is well below the anticipated sale price.
“The result is that when buyers are searching up to a maximum prescribed value, properties that are well above that range are still appearing in the search feed for buyers and this is extremely misleading, but agents do it to attract more buyer interest.”
Timely taskforce
In Victoria, CAV has this week launched a $3.8 million taskforce to target unfair practices in the property market, including underquoting.
It will include existing and additional officers with a range of skills and experience including inspectors, investigators, information analysts, and legal officers.
“The creation of the dedicated underquoting taskforce builds on significant regulatory activity undertaken in May 2021, where inspectors made unannounced visits to 29 metropolitan and regional estate agents’ offices to monitor their compliance with underquoting laws,” a Victorian Government spokesperson said.
Since 2015, Consumer Affairs Victoria has taken court action and accepted enforceable undertakings from 13 real estate agencies, with fines and court costs totalling more than $3 million.
Underquoting was identified as a key concern by the Victorian property market review, the findings of which are currently being considered by Government.
Submissions for the review closed on 1 April. The Victorian Government spokesperson told API Magazine that it was still to be completed.
“The Government is considering the findings of the review alongside changing market conditions and will have more to say about this work soon,” the spokesperson said.
Significant penalties, including fines of more than $36,000, apply for underquoting. Underquoting can also result in penalties under the Australian Consumer Law of up to $10 million for corporations and $500,000 for individuals.
Perth and Brisbane may be on opposite sides of Australia but the roughly two million inhabitants in each city enjoy a lifestyle centred on sizeable properties or modern apartments, plenty of sunshine and good public facilities, schools and universities.
They’re two cities of similar size, climate and lifestyle yet with very different property investment outlooks for 2022.
Perth and Brisbane may be on opposite sides of Australia but the roughly two million inhabitants in each city enjoy a lifestyle centred on sizeable properties or modern apartments, plenty of sunshine and good public facilities, schools and universities.
The deeper you dig, the more the economic parallels emerge too. They are the sibling cities that moved as far from each other geographically as the continent would allow. They’re actually more like twins, being the same age, doing the same jobs and incurring the same property debts.
It’s almost spooky how alike they are.
Each city has a median age of 34-35 years, and each has 63 per cent of their over 15s in the workforce. Uncannily, the top three occupations of employed persons are identical, with professionals at 22 per cent of the workforce, managers at 11 per cent, and labourers nine per cent.
When it comes to housing costs for their roughly 800,000 dwellings each, the two cities are also on a par.
Perth households spend 28.4 per cent of their household incomes on the mortgage or 21.9 per cent of their incomes on the rent. That figure hardly changes for Brisbane, at 27.8 per cent and 22.7 per cent respectively.
Both cities held off COVID in 2021 and had economies that tracked along reasonably well.
So why are property investors and intrastate migrants pouring into Brisbane and largely overlooking Perth?
Tale of two cities
Even though property price growth is slowing in other parts of Australia, Brisbane’s housing markets are likely to continue to perform strongly in 2022.
Both markets are coming off years of lean performance, but it is Brisbane that is outshining its sibling now.
Buyers agent Grant Foley, of Grant Foley Property, said Greater Brisbane has enormous momentum and is experiencing a much-awaited cyclical price boom.
“With significant runway still existing for growth, I expect prices to rise by a further 10 to 15 per cent in 2022, fuelled by not only strong local sentiment, but also continued interstate migration and investor activity.”
Perth’s housing market looks to have temporarily stabilised after a strong run of growth, with housing values edging 0.2 per cent higher last month and 0.4 per cent higher over the rolling quarter.
Across the capitals, the monthly change last month ranged from a 0.1 per cent fall in Melbourne housing, through to a top-of-the-table 2.9 per cent surge in Brisbane dwelling values.
CoreLogic’s Research Director Tim Lawless said Brisbane and Adelaide, along with regional Queensland, are the only broad regions where there is no evidence of prices slowing just yet, with the monthly rate of growth reaching a new cyclical high in December.
“While the pace of capital gains has been easing in Sydney, Melbourne and Perth, conditions across the Brisbane and Adelaide housing markets have gathered momentum,” Mr Lawless said.
“Slower conditions across the Perth housing market may be more attributable to the disruption to interstate migration caused by extended closed state borders, which has had a negative impact on housing demand.
“In Brisbane, housing affordability is less challenging, advertised stock levels remain remarkably low and demographic trends continue to support housing demand,” he said.
Julie Kelley, Sales and Marketing Manager of SMATS Group, said the southeast Queensland housing market was booming, with huge buyer competition, prices rising quickly and days on market at historical lows.
“Those wanting to repatriate are seeing sense in buying before they return to Australian shores for a number of reasons — they don’t want to be priced out of the market, children have school commitments set for a particular date, they understand it will take time to settle and that if their shipping is delayed, reliance on securing short term rental accommodation is difficult,” Ms Kelley said.
Fun and games
So, despite their overt similarities, the widely held view is that Perth will grow at around three to five per cent in 2022, most pundits are predicting rises of 10 to 15 per cent for Brisbane.
The influx of migrants from Sydney and Melbourne into Brisbane is partly due to its relative closeness compared to Perth but is also a reflection of economic confidence.
Perth has benefited greatly from jobs generated by a record iron ore price but it’s that same sector that is also of the greatest concern to potential residents and property investors.
Property analyst and commentator Gavin Hegney told Australian Property Investor Magazine he perceived two main differences between the Perth and Brisbane markets.
“Queensland is seen to have a more diversified economy and, secondly, they will have a global advertisement running for the next six years or so in the Olympic Games,” he said.
“Perth has high rental yields, has not seen excessive growth pushing the market beyond fair value and is likely to have an uplift in values with opening borders given the strong employment market.
“While there has been some good growth at the top end, the level of investor activity is extremely low, and has been in recent years.
“A shortening supply of land and rising building costs are putting cost pressures on the market and at this stage apartment values haven’t risen as fast as costs and hence feasibilities aren’t tending to promote development.
“These factors make it extremely unlikely that the market will be oversupplied.”
One-trick pony
Perth’s perception as a one-trick pony economically is based on its increasingly unhealthy mining export reliance on China.
Australia’s fraught relations with its largest trading partner are only serving to highlight this more each year. Iron ore prices have also fallen back to more traditional levels.
In the early 2000s, China represented less than 20 per cent of Western Australia’s international exports. Today that figure is in excess of 70 per cent, with few outward signs of the State Government redressing the imbalance.
Chamber of Commerce and Industry WA CEO Chris Rodwell told API Magazine that their own nation-wide polling showed WA had become a significantly more attractive business investment destination but would benefit greatly from a more diversified economy.
“Nearly three in five businesses in Australia (57.3 per cent) reported being more interested in investing in WA in 2021, particularly businesses in New South Wales, and that interest arose across the financial and insurance services, professional and technical services and renewable energy,” Mr Rodwell said.
“It doesn’t arise solely from the mining sector, which is encouraging because it’s just the sort of activity we need in order to diversify our economy.
“What those businesses indicate they like about WA is the lifestyle (40 per cent), the strength of the local consumer economy (34 per cent), and strong well-managed state finances (24 per cent).
He said a key to attracting further investment and migration was to ensure WA strengthened its tax and regulatory environment.
“Diversifying our economy remains WA’s top priority, and payroll tax reform would particularly enable medium-sized businesses in sectors like manufacturing, construction and agribusiness to grow.”
The recently released ANZ Corelogic Housing Affordability Report showed the wide scale decline in housing affordability with the ratio of housing values to household income reaching a new record. This was coupled with the number of years it takes to save for a deposit and the ratio of income to rent.
Buyers in regional Australia have been particularly strained due to the effects of COVID-19, with remote work trends and appealing coast and tree changes have become the new normal, and raised regional investing and purchasing to new levels.
Migration from cities to regions increased almost 6% by March 2021, and was up 14.3% from the decade average compared to a 3.5% decline leaving regional Australia to capital cities.
Eliza Owen, Head of Research at Corelogic said where a loss of momentum across capitals was usually matched by easing growth of regional Australia there has been a clear divergence in recent months. This was probably due to major cities coming out of lockdowns & the easement of social distancing and travel restrictions.
“Interestingly, the latest CoreLogic home value index results show that dwelling value and rent growth across the regions shows no sign of slowing just yet. Over November, dwelling values in regional Australia increased a further 2.2%, up from 1.9% in the previous month, and twice the monthly growth rate of capital city markets in November.”
MCG Quantity Surveyors recently conducted their latest Property vs Postal survey highlighting the increase in remote and borderless investing due to the global pandemic. The study indicated investors had ‘doubled the distance’ between where they live and where they invest.
Mike Mortlock, managing director of MCG Quantity Surveyors, compared the buying habits of their investor clientele for 2020 and then again in the year to November 2021 showing the average distance from investor home to investment property had risen from 294km pre-COVID to 559km over the pandemic period.
“Rather than going to ground during lockdowns, it seems investors looked for real estate opportunities further from their home suburbs than ever before.
“What’s perhaps most telling is the rapid increase in those looking for assets positioned exceptional distances from their home.
“Buyers investing in locations more than 200 kilometres from home rose from 29.5 per cent in January 2020 to 44.65 per cent in November 2021.
“Even more dramatically, the percentage investing more than 1000 kilometres from home more than doubled during the period.”
Property vs. Postal
% of investors
Jan 2020
Nov 2021
Invest in same suburb*
6.9%
6.75%
further than 200km
29.5%
44.65%
further than 1,000km
7.7%
17.15%
closer than 50km
60.1%
41.12%
closer than 10km
36.1%
19.1%
closer than 5km
23.2%
11.56%
closer than 2km
10.8%
4.99%
Average Distance
293.47km
559.09km
Sample size
994
822
*Principle place of residence. Source: MCG Quantity Surveyors.
Only 6.75% of Australian-based investors bought within their primary residence suburb, with most popular investment destination being Queensland with over 37% of investors buying in the sunshine state.
Mr Mortlock said a range of factors had made distance buying an attractive option.
“Firstly, lockdowns and economic uncertainty during the pandemic has had Australians thinking long and hard about their financial situation, so investing has been front of mind.
“Technology makes it possible to buy property from the comfort of a locked-down home. Modern day investors see the whole of Australia as a potential market – not just their state or city.
“Also, the surging popularity of regional relocation in this remote working world has boosted those property markets. Capital growth rates in many regional centres rivalled big cities in 2021, and investors want to get a piece of this action.”
Purchasing properties ‘sight unseen’ has become more prevalent with the ease of engaging local buyer’s agents in the suburbs you want to invest in, regardless of where you live. An upswing in buyer’s agent engagement amongst investors has shown the they rely on advice on where and what to buy, the facts and figures and less about the emotional connotations of location.
Julie Kelley, Buyers Agent at Aussieproperty.com has noticed the increased demand for buyers agents from not just international/expat buyers but the local market, with residents from WA, VIC and NSW all showing interest in QLD properties.
‘I’ve had cash buyers ready to purchase apartments without even seeing a picture, let alone getting a local walkthrough of the property.”
Whilst based on the west coast, with a vast network of professionals around Australia Ms Kelley has been able to get local agents to provide walkthroughs and conduct due diligence on behalf of her clients.
“We are able to get offers done faster than ever before because the interest and subsequent trust of Buyer’s Agents has certainly been evidenced,’
“I’ll work with one client, and within a week or two of settlement I’m getting a call from one of their referrals for assistance, as well as assisting with property management and future investment planning”.
What many are now speculating on is whether this trend will be sustained once borders reopen and life returns to pre-pandemic ‘normal’, its only a matter of time to see what happens.